


I’ve been looking through some new Alibaba notes/research from Citi and Nomura this week and wanted to share my thoughts on their estimates and how they compare with what I’m expecting.
I’m still bullish, obviously. Roughly 50% cloud growth is the assumption I’m working with for the September quarter, and I’m hoping to see cloud EBITA margins continue trending higher after we finally got a meaningful increase last quarter.
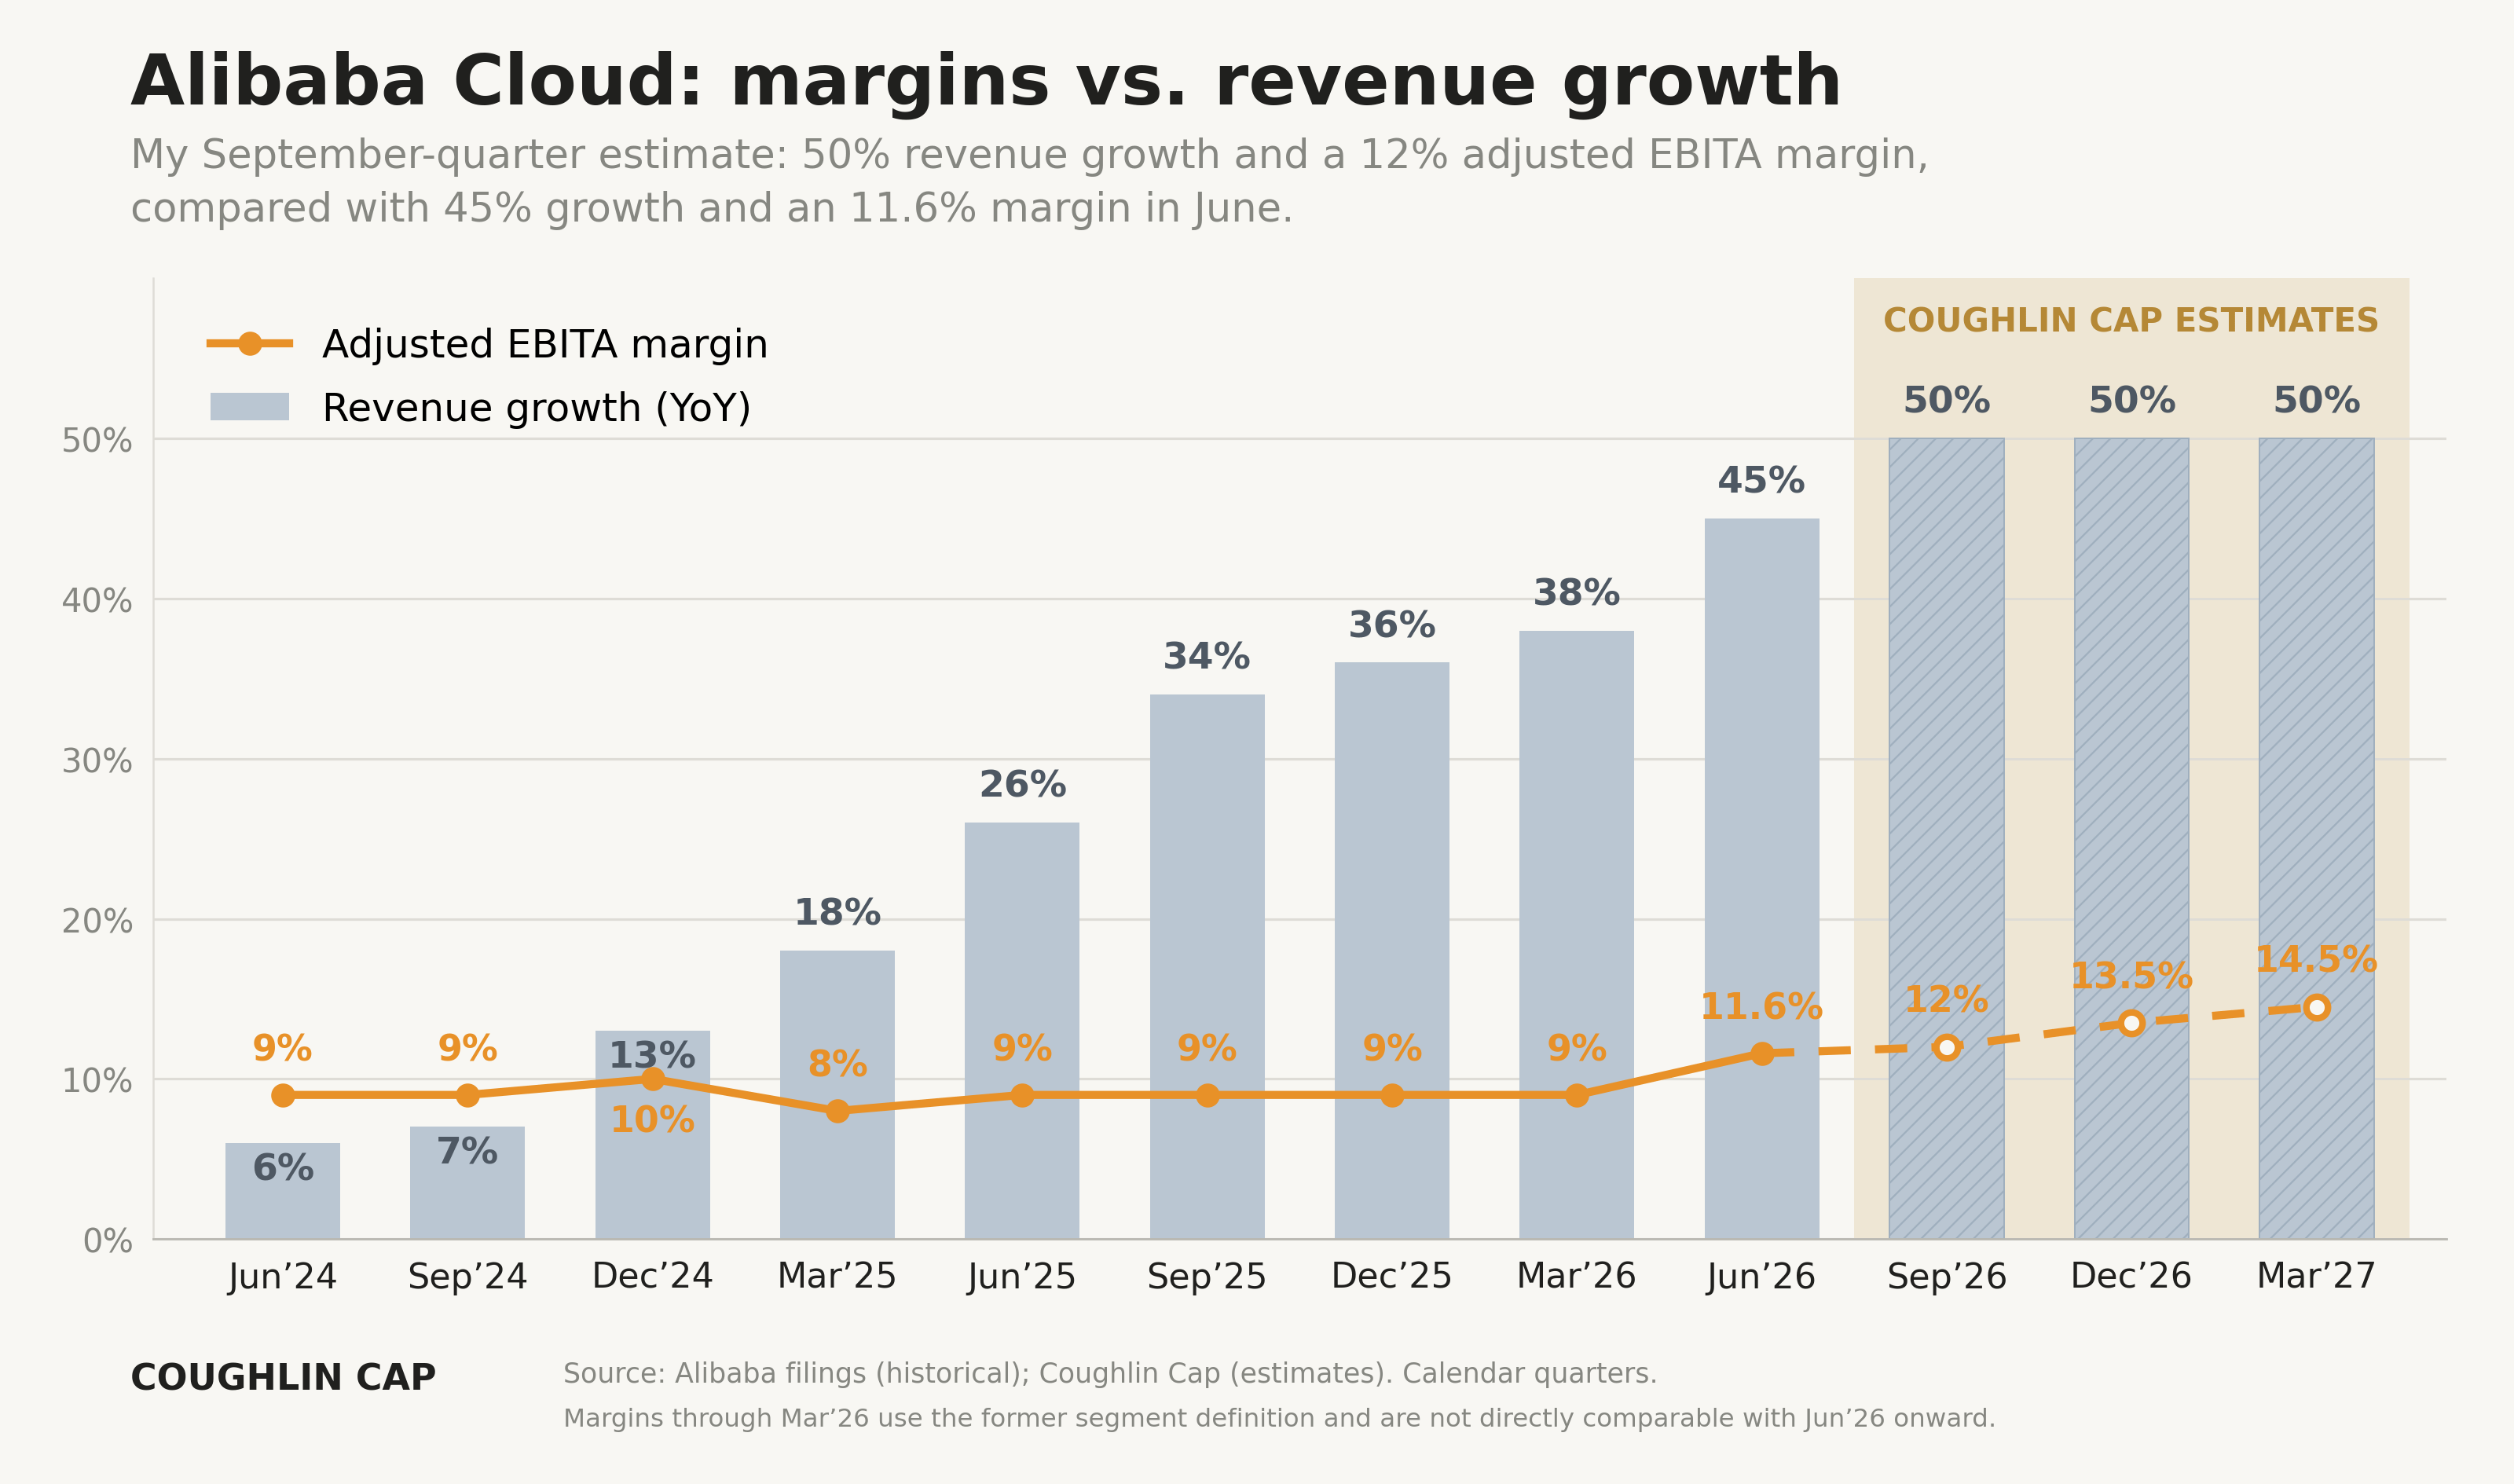
I also continue to think quick-commerce losses can narrow fairly quickly from here, helping e-commerce profitability recover. Some of the earnings revisions below point in that direction, though there’s still plenty Alibaba needs to deliver on.
Citi
Citi maintained its Buy rating and raised its target from $190 to $193. Its September-quarter forecast has cloud revenue growing 52%, with a 12.5% EBITA margin. That margin estimate was raised from 12% and compares with 11.6% in the June quarter.
That’s pretty close to what I’m looking for. Around 50% growth would be a strong result on its own, but I’d like to see Alibaba convert more of that growth into earnings as the business gets larger. Last quarter gave us some real improvement in margins. I want to see them build on it, even if the next increase is more gradual.
Citi also expects the growth to hold up beyond this quarter. Its model has cloud revenue growing 54% in FY27 and 52% in FY28. For reference, Alibaba’s FY27 ends in March 2027 and FY28 ends in March 2028.