


I’ve been wrong on Shift4 so far. I thought it was cheap at much higher prices and bought too early. It’s been an awful stock to own, and being bullish on the business hasn’t made that any less painful.
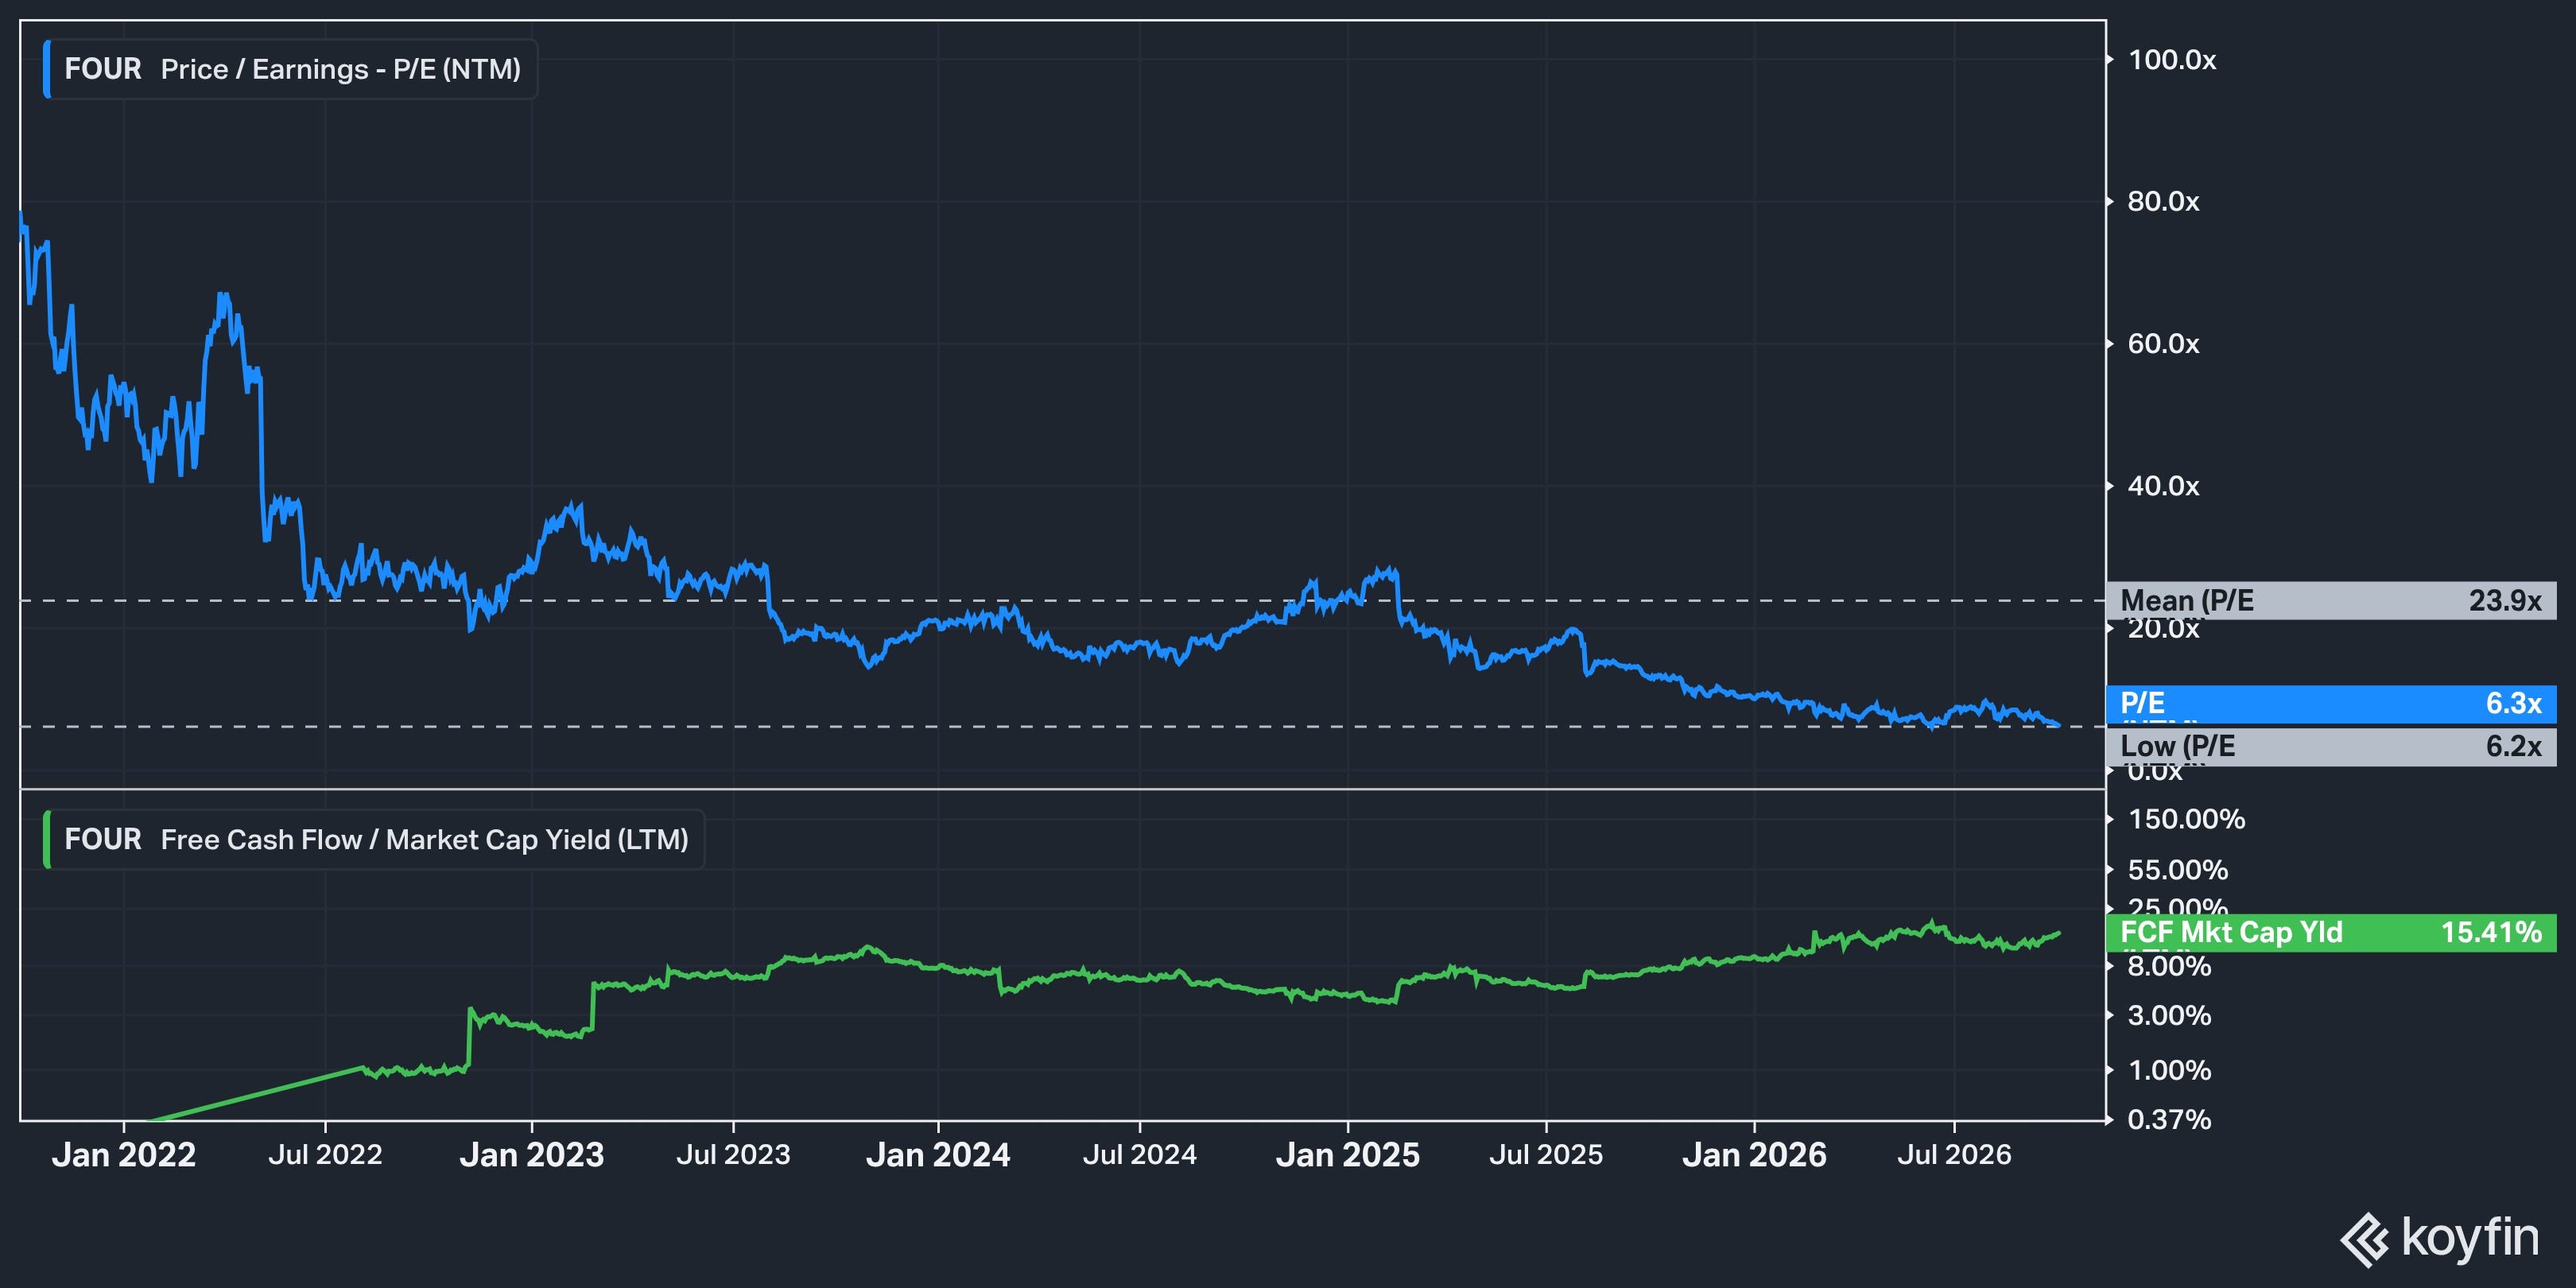
The market clearly disagrees with me, and I’m probably being a bit stubborn. But at roughly ~6.5x forward earnings and a ~15% trailing free cash flow yield, I’m still very confident FOUR is too cheap.
There are legitimate concerns about the business, and I’ve underestimated how much those would weigh on the stock. I just think the price now reflects a level of pessimism that the business doesn’t deserve. It’s trading like it’s dying, and I don’t see that in the results.
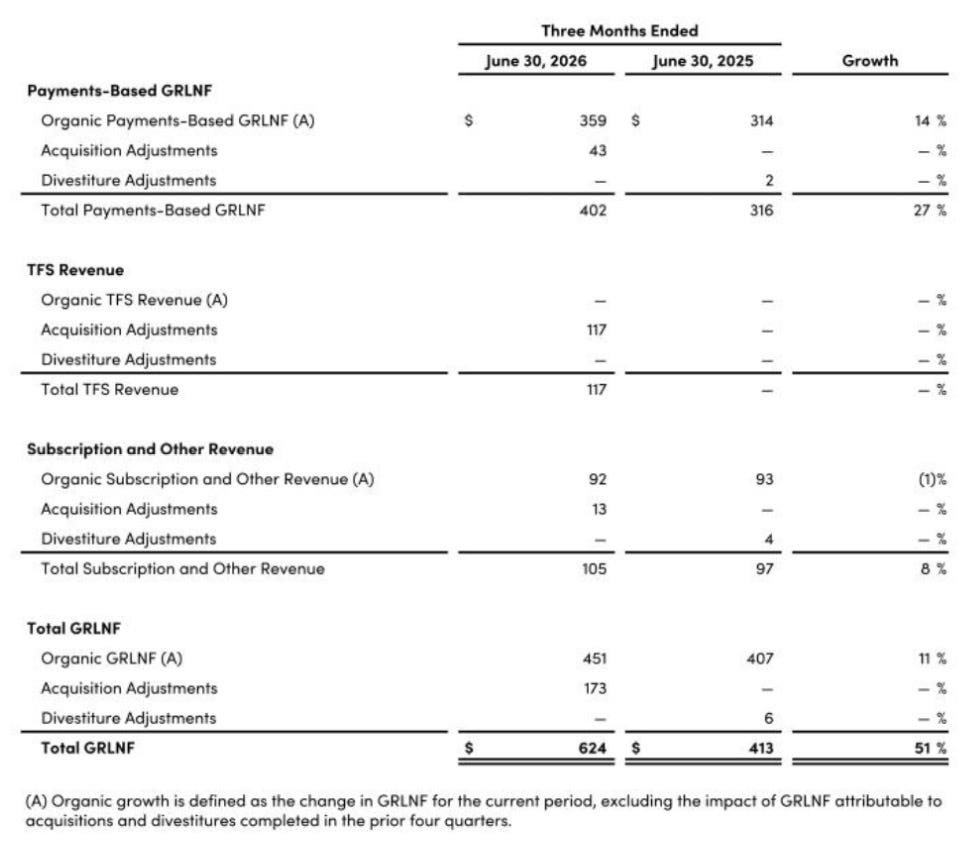
A big reason for the discount is that people don’t trust the growth. Organic growth in revenue less network fees was 11% overall in Q2, with the payments business growing 14%. That’s a lot less exciting than the acquisition-heavy headline numbers, and some investors argue even the organic figures overstate how well FOUR can grow without buying another company.
The concern is that Shift4 acquires a business with an existing merchant base, converts those merchants to its payment processing, and gets a few years of growth from doing so. Once those conversions slow down, it needs another acquisition to keep things moving. Growth from older acquisitions can still count as organic, so the reported number doesn’t settle that debate. I think that’s a fair thing to question.
I’m just not nearly as negative about the strategy or the organic growth they can generate from here. I think there’s still a lot they can do with the businesses they already own, particularly Global Blue.
Global Blue gives them established retail relationships where they can sell payment processing alongside tax-free shopping. A retailer already using Global Blue for tax refunds could still be using someone else to handle its payments. Winning that processing would let Shift4 earn more from an existing customer without needing another acquisition. Shift4 One combines payments, tax-free shopping and currency conversion on one device, and it was already live in 12 European countries at the Q2 update.
There’s also an opportunity to use that international presence to win customers beyond the businesses they acquired.
Management has explained that getting the payments infrastructure operating in those countries makes it easier to introduce other products, and Shift4 Dine has already launched in Spain and Australia. I think that gives them room to keep growing as they sell more services to existing merchants and compete for new ones. I’m more optimistic about how much growth they can get from those opportunities than the current sentiment would suggest.